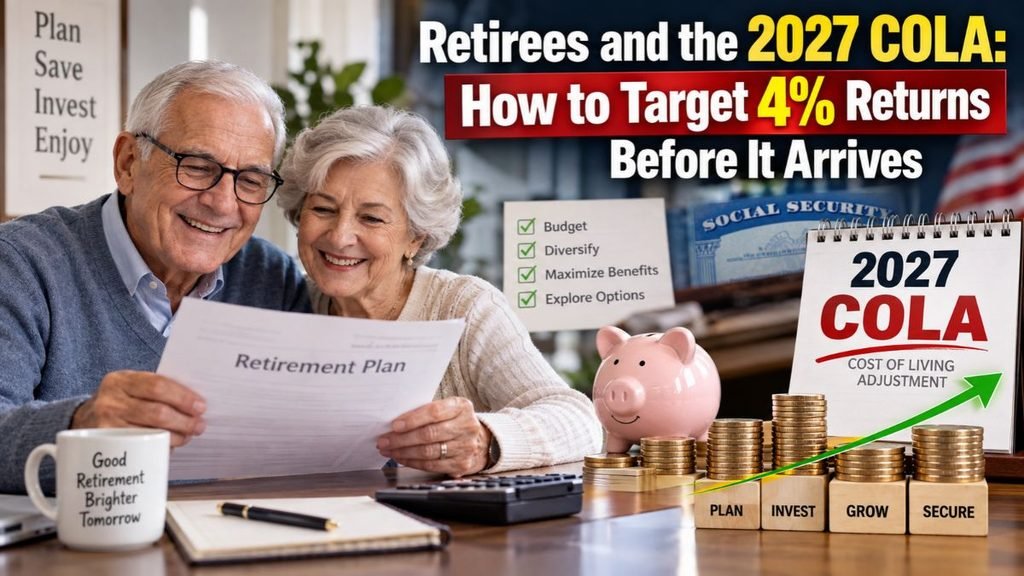
After retirement, it’s usually mostly about managing that regular income so day to day expenses are covered, but savings stays safe, and ready, in the long run. On top of that, rising inflation really makes it harder, because everything costs a bit more. So, some retirees may start looking at a plan that tries to target a 4% return, say, up to the 2027 COLA , (Cost-of-Living Adjustment) . Yet a 4% return isnt something anyone can count on, and every investment comes with some uncertainty. So, you have to weigh things like your age, how much you’ve saved, your monthly spending, and your own risk comfort level, before you lock in any kind of target.
Understand the 4% return
While aiming for a 4% return might sound pretty simple, it does not actually lock in a fixed 4% gain from investments every single year, no. Market-linked products, they can swing around, sometimes a lot. For retirees, finding that middle road between keeping the capital safe and still getting steady income is often more important than just chasing higher returns, like purely, end of story. Before choosing any investment, it’s crucial to get what level of risk is being accepted in exchange for the potential returns , because that part matters more than it seems at first.
Why is planning before the 2027 COLA important?
While aiming for a 4% return might sound pretty simple, it does not actually lock in a fixed 4% gain from investments every single year, no. Market-linked products, they can swing around, sometimes a lot. For retirees, finding that middle road between keeping the capital safe and still getting steady income is often more important than just chasing higher returns, like purely, end of story. Before choosing any investment, it’s crucial to get what level of risk is being accepted in exchange for the potential returns , because that part matters more than it seems at first.
Consider low-risk options
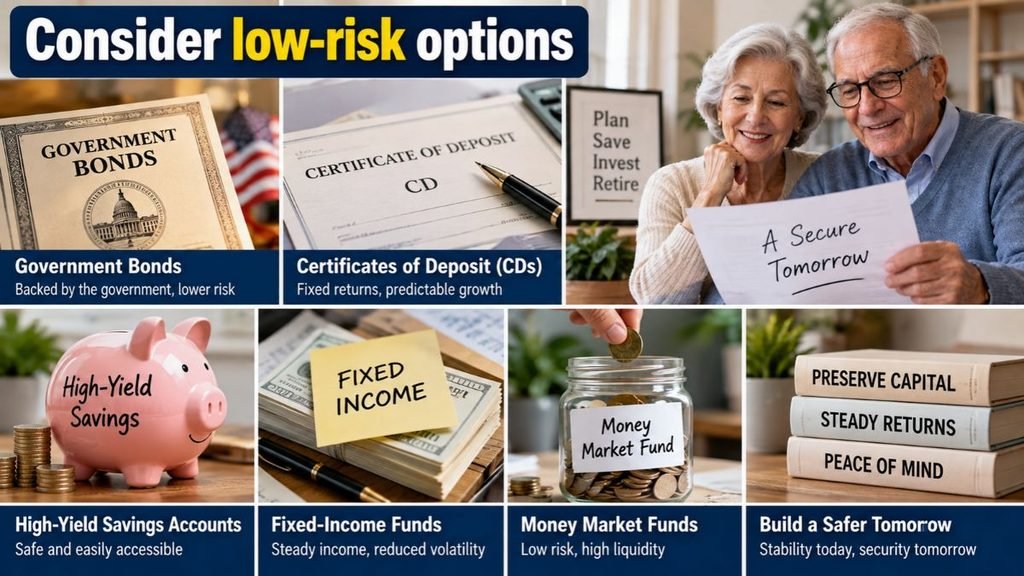
Putting all of your savings into high-risk assets when retirement is getting closer, or even after you’ve retired, might not be the best move. Some people prefer to blend in steadier choices like Treasury securities, CDs, or other comparatively low-risk instruments into what they live off of. When you pick among these, you really need to look at things like current interest rates, the length or tenure of each option, tax implications, and also when you might need the money later on, not just now. In general the aim shouldn’t only be “hit a 4% return”, it should be to build a setup where you’re not pressured to sell your investments at a loss when cash is suddenly required.
Maintain portfolio balance
Carrying a blend of different asset types inside a retirement portfolio can help smooth out risk, at least in a practical way. You might put part of your money into instruments that are fairly steady, and then move the rest toward opportunities meant for long term expansion. Honestly the best ratio really depends on the person, because needs are never the same. Like if you’re a retiree and you have to pull withdrawals from your investments in the near term, your overall plan likely looks different than the plan for someone who already has other income coming in, so the pressure is less.
Do not overlook inflation
If an investment brings in 4% return but the cost of living surges during that same period, the real gain may end up being a lot smaller. So, when you’re planning for retirement, you really have to look at actual purchasing power alongside the nominal return, not just the headline number. And yes, it helps to include the rising costs, like healthcare, household expenses, insurance, food, and other necessities, directly into your budget early on—so later you’re not hit with unexpected financial pressure.
The importance of regular income and cash reserves
Keeping enough liquid savings around so you can pay expenses for a few months , maybe even a couple years once retirement starts, can be pretty helpful. The idea is that you don’t always have to sell investments just to cover day to day spending especially if markets get wobbly. In other words, cash reserves should be baked into the plan, particularly when you’re aiming for a 4% return. If you count on investment gains alone, it can raise the overall risk, and that’s the part people often forget.
Understand the impact of taxes and fees
The promised return on a investment isn’t always the number you end up keeping. Taxes, account charges, and a few other costs can really shift your final earnings, sometimes in ways that look small at first but add up. So, instead of staring only at the advertised return it is better, kind of calmer to look at the after tax and after fee outcome when you pick an investment, and then you know what you’re actually retaining, not just what the brochure says.
Be prepared for market downturns
A pretty big market drop once you are in retirement can kind of trigger worry, in particular if you also have to pull money out for usual expenses right when it happens. So, it becomes really important to plan ahead for those downturns, inside your overall investing approach, even if it sounds a bit pessimistic. Having a diversified portfolio and keeping solid emergency reserves can ease some of the stress financially, because you have options, and you are not forced into the move too quickly.
Keep the 4% target flexible
It is kinda not possible to get a perfect return of exactly 4% every year. Like one year the investments might look really good, then the next year you could still face losses, even with the same approach. So it is better to treat that 4% number as sort of a planning north star, not as a guaranteed income stream. You may need to finetune your strategy , depending on what is happening in the markets, how interest rates move around, and also your own personal expenses, over time.
Personal planning is paramount
Every retiree’s financial situation is kind of unique, like it really depends. Some people may have a pension along with Social Security, while others may lean more on rental cash flow or a big stash of savings. In the same way healthcare requirements can swing quite a lot from one person to the next. So before you set a 4% return target ahead of the 2027 COLA, it seems smart to look over your whole financial picture first. If it feels messy or you just want a second opinion, talking with a qualified financial professional can help, too.
Conclusion
Trying to get a 4% return before the 2027 COLA adjustment , can be a helpful planning yardstick for some retirees, though it shouldnt be treated like a fixed, or guaranteed paycheck. Once you’re in retirement, the big thing isnt only chasing bigger returns—its more about finding that sensible equilibrium between earnings, keeping principal intact, guarding against inflation, and managing risk. A solid plan is usually the one that stays adjustable, so it can shift with the shifting markets, and also with the persons real life requirements.
FAQs
Q1. What is the 2027 COLA?
A. The 2027 COLA is a cost-of-living adjustment intended to help Social Security benefits keep pace with inflation.
Q2. Can retirees guarantee a 4% return?
A. No. A 4% return is a target, not a guaranteed outcome, and investment returns can fluctuate.
Q3. How can retirees prepare for the 2027 COLA?
A. Retirees can review their budget, maintain emergency savings, and balance income needs with investment risk.