2027 VA Disability Rates: What Veterans Need to Know
For veterans who rely on VA disability compensation, annual rate changes can make a meaningful difference to monthly household budgets. The 2027 VA disability rates are expected to increase because VA compensation rates are adjusted in line with Social Security cost-of-living adjustments, commonly known as COLA. However, the official 2027 VA payment tables have not yet been released, so veterans should be careful when looking at estimated figures online. The U.S. Department of Veterans Affairs confirms that disability compensation depends on a veteran’s disability rating as well as factors such as qualifying dependents.
How VA Disability Compensation Rates Work
VA disability compensation is generally based on the severity of a service-connected disability. VA assigns disability ratings from 0% to 100% in 10% increments, and the monthly payment increases as the disability rating rises. Veterans with ratings of 30% or higher may also receive additional compensation when they have qualifying dependents, such as a spouse, child, or dependent parent. Certain veterans with particularly severe disabilities may qualify for Special Monthly Compensation, which can provide additional payments beyond the standard disability compensation rate.
What Could Change in 2027?
The main factor expected to affect the 2027 VA disability rates is the annual COLA adjustment. By law, VA disability compensation and pension rates are adjusted using the same percentage as Social Security benefits. The Social Security Administration’s 2026 Trustees Report currently projects a 2.4% COLA for 2027, but this is only an estimate and is not the final COLA determination.
Because the final adjustment has not yet been determined, it would be misleading to treat projected 2027 payment amounts as official VA rates. Once the applicable COLA is finalized, VA will publish updated compensation tables showing the new monthly amounts for different disability ratings and dependent situations.
Why Your Payment May Differ From Another Veteran’s
Two veterans with the same disability rating may receive different monthly amounts because their family circumstances can be different. For example, qualifying spouses, children, or dependent parents can affect compensation for veterans with a rating of 30% or higher. Additional amounts may also apply in certain situations, including when a spouse qualifies for Aid and Attendance.
Other circumstances can affect payments as well. VA notes that military retirement pay, disability severance pay, separation pay, and certain periods of incarceration may affect the amount a veteran receives. This is why a simple disability percentage alone does not always tell the complete story of a veteran’s monthly compensation.
When Veterans Can Expect Updated Rates
VA compensation rates generally become effective on December 1 following the applicable annual COLA adjustment. The current VA rate tables, for example, show the 2026 compensation rates as effective December 1, 2025. Veterans should therefore watch the official VA compensation-rate tables for the release of the 2027 figures rather than relying on unofficial charts or social media posts.
Final Thoughts
The 2027 VA disability rates are expected to be higher than the current rates if the projected COLA results in an increase, but the exact payment amounts cannot be confirmed until the official adjustment and VA tables are released. Veterans should consider their disability rating, dependent status, and any special compensation eligibility when estimating future payments. Checking VA.gov for the latest official rate tables is the safest way to confirm the amount that applies to an individual situation.
FAQs
Q1: What are 2027 VA disability rates?
A1: Rates depend on disability rating and dependents.
Q2: When will 2027 VA rates update?
A2: Updated rates follow the annual COLA adjustment.
Q3: Will VA disability payments increase in 2027?
A3: Payments may increase following the annual COLA.
VA Disability Increase 2027: What Veterans Need to Know
VA disability benefits are kind of a major income source for hundreds of thousands of American veterans and their families. Disability compensation rates can be updated each year via a Cost-of-Living Adjustment, also called a COLA, to help with the rising cost of living. The “final” VA disability increase for 2027 has not been officially set yet. Still, looking at the middle estimates from the 2026 Social Security Trustees Report, the projected COLA for 2027 is being figured out at about 2.4%. Budget-related VA documents also suggest the COLA for folks getting disability compensation is tied to the adjustment Social Security beneficiaries receive.
What might the 2027 VA disability increase look like?
If the current estimate of 2.4% is used as the final COLA, eligible veterans could end up seeing something like a 2.4% jump in their monthly disability compensation. Like, for example, if someone is currently receiving $2,000 per month, that 2.4% increase would work out to an extra $48 per month. But it is not that clean cut, because the real amount hinges on things such as the veteran’s disability rating, their dependent status, and whichever VA compensation rate is the relevant one. So, it would be wrong to just assume one same dollar bump across the board for all veterans, only because the percentage looks the same.
How is the COLA determined?
The annual COLA for VA disability compensation isn’t something picked out of thin air or by arbitrary estimation. In official VA budget documents it’s basically tied to the Consumer Price Index, and then it’s linked to the adjustment Social Security beneficiaries get. So that currently available 2.4% number is more like a projection, not the actual, final rate. What the final 2027 adjustment will look like, will only get clearer once the relevant inflation data starts coming in, and you know, gets used.
How might this affect veterans’ payments?
Once the final COLA is kind of determined, changes will be reflected in the compensation rates that are applicable to different disability ratings and dependent categories. So instead of relying only on the headline percentage , veterans really should look at the new rate table for their particular VA payment category. Even a small percentage increase can end up making a big difference in total payments over the course of the year.
What should be kept in mind regarding the 2027 increase?
For veterans, it is kinda crucial to understand the distinction between what is being projected right now and the official rate for 2027, because otherwise it feels like you know more than you actually do. The 2.4% projection should not be seen as some guaranteed payment amount, it’s more like an estimate, and the exact change in monthly payments per rating category will only become clear once the VA releases its final compensation tables. Also, since the rules and the amounts for certain other veteran benefits can differ from disability compensation, you really should consult the official info that is specific to each benefit, not just what people usually say.
Conclusion
While the 2.4% COLA projection for the 2027 VA disability increase is sort of a current conversation, it can’t really be treated as the final number. The SSA’s 2026 Trustees Report gives this 2.4% COLA projection, and the VA paperwork suggests that the disability compensation COLA is tied to the Social Security adjustment. So yeah, veterans should wait for the final VA announcement and the revised compensation tables before trying to pin down exactly what changes, on their monthly payments, for 2027.
FAQs
Q1. Will VA disability benefits increase in 2027?
A. A 2027 increase is expected, but the final COLA percentage has not yet been officially announced.
Q2. How is the VA disability increase determined?
A. VA disability compensation COLA is generally tied by law to the Social Security COLA.
Q3. When will the 2027 VA increase be confirmed?
A. The final adjustment will be confirmed after the official 2027 COLA is announced.
Retirees and the 2027 COLA: How to Target 4% Returns Before It Arrives
After retirement, it’s usually mostly about managing that regular income so day to day expenses are covered, but savings stays safe, and ready, in the long run. On top of that, rising inflation really makes it harder, because everything costs a bit more. So, some retirees may start looking at a plan that tries to target a 4% return, say, up to the 2027 COLA , (Cost-of-Living Adjustment) . Yet a 4% return isnt something anyone can count on, and every investment comes with some uncertainty. So, you have to weigh things like your age, how much you’ve saved, your monthly spending, and your own risk comfort level, before you lock in any kind of target.
Understand the 4% return
While aiming for a 4% return might sound pretty simple, it does not actually lock in a fixed 4% gain from investments every single year, no. Market-linked products, they can swing around, sometimes a lot. For retirees, finding that middle road between keeping the capital safe and still getting steady income is often more important than just chasing higher returns, like purely, end of story. Before choosing any investment, it’s crucial to get what level of risk is being accepted in exchange for the potential returns , because that part matters more than it seems at first.
Why is planning before the 2027 COLA important?
While aiming for a 4% return might sound pretty simple, it does not actually lock in a fixed 4% gain from investments every single year, no. Market-linked products, they can swing around, sometimes a lot. For retirees, finding that middle road between keeping the capital safe and still getting steady income is often more important than just chasing higher returns, like purely, end of story. Before choosing any investment, it’s crucial to get what level of risk is being accepted in exchange for the potential returns , because that part matters more than it seems at first.
Consider low-risk options
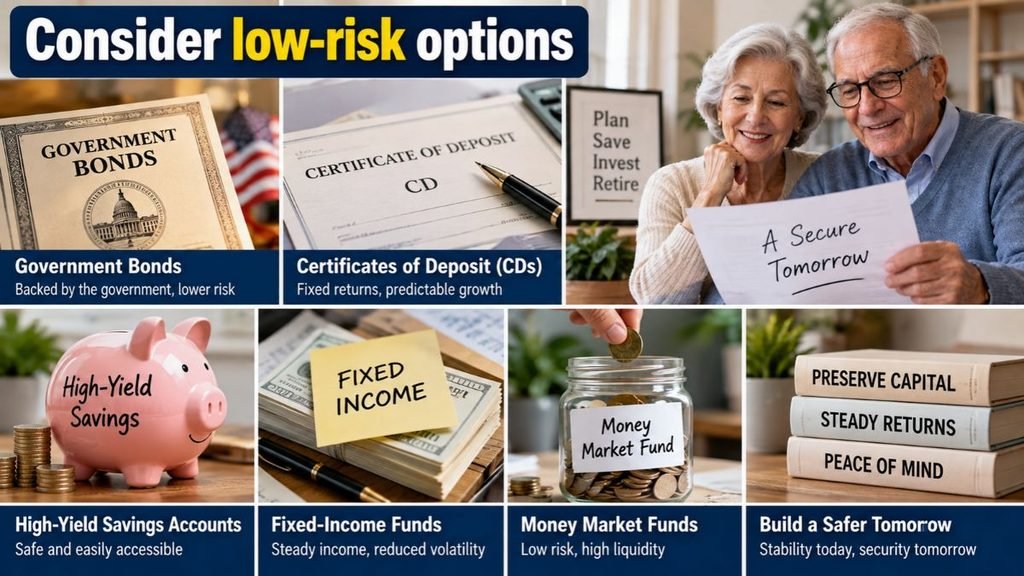
Putting all of your savings into high-risk assets when retirement is getting closer, or even after you’ve retired, might not be the best move. Some people prefer to blend in steadier choices like Treasury securities, CDs, or other comparatively low-risk instruments into what they live off of. When you pick among these, you really need to look at things like current interest rates, the length or tenure of each option, tax implications, and also when you might need the money later on, not just now. In general the aim shouldn’t only be “hit a 4% return”, it should be to build a setup where you’re not pressured to sell your investments at a loss when cash is suddenly required.
Maintain portfolio balance
Carrying a blend of different asset types inside a retirement portfolio can help smooth out risk, at least in a practical way. You might put part of your money into instruments that are fairly steady, and then move the rest toward opportunities meant for long term expansion. Honestly the best ratio really depends on the person, because needs are never the same. Like if you’re a retiree and you have to pull withdrawals from your investments in the near term, your overall plan likely looks different than the plan for someone who already has other income coming in, so the pressure is less.
Do not overlook inflation
If an investment brings in 4% return but the cost of living surges during that same period, the real gain may end up being a lot smaller. So, when you’re planning for retirement, you really have to look at actual purchasing power alongside the nominal return, not just the headline number. And yes, it helps to include the rising costs, like healthcare, household expenses, insurance, food, and other necessities, directly into your budget early on—so later you’re not hit with unexpected financial pressure.
The importance of regular income and cash reserves
Keeping enough liquid savings around so you can pay expenses for a few months , maybe even a couple years once retirement starts, can be pretty helpful. The idea is that you don’t always have to sell investments just to cover day to day spending especially if markets get wobbly. In other words, cash reserves should be baked into the plan, particularly when you’re aiming for a 4% return. If you count on investment gains alone, it can raise the overall risk, and that’s the part people often forget.
Understand the impact of taxes and fees
The promised return on a investment isn’t always the number you end up keeping. Taxes, account charges, and a few other costs can really shift your final earnings, sometimes in ways that look small at first but add up. So, instead of staring only at the advertised return it is better, kind of calmer to look at the after tax and after fee outcome when you pick an investment, and then you know what you’re actually retaining, not just what the brochure says.
Be prepared for market downturns
A pretty big market drop once you are in retirement can kind of trigger worry, in particular if you also have to pull money out for usual expenses right when it happens. So, it becomes really important to plan ahead for those downturns, inside your overall investing approach, even if it sounds a bit pessimistic. Having a diversified portfolio and keeping solid emergency reserves can ease some of the stress financially, because you have options, and you are not forced into the move too quickly.
Keep the 4% target flexible
It is kinda not possible to get a perfect return of exactly 4% every year. Like one year the investments might look really good, then the next year you could still face losses, even with the same approach. So it is better to treat that 4% number as sort of a planning north star, not as a guaranteed income stream. You may need to finetune your strategy , depending on what is happening in the markets, how interest rates move around, and also your own personal expenses, over time.
Personal planning is paramount
Every retiree’s financial situation is kind of unique, like it really depends. Some people may have a pension along with Social Security, while others may lean more on rental cash flow or a big stash of savings. In the same way healthcare requirements can swing quite a lot from one person to the next. So before you set a 4% return target ahead of the 2027 COLA, it seems smart to look over your whole financial picture first. If it feels messy or you just want a second opinion, talking with a qualified financial professional can help, too.
Conclusion
Trying to get a 4% return before the 2027 COLA adjustment , can be a helpful planning yardstick for some retirees, though it shouldnt be treated like a fixed, or guaranteed paycheck. Once you’re in retirement, the big thing isnt only chasing bigger returns—its more about finding that sensible equilibrium between earnings, keeping principal intact, guarding against inflation, and managing risk. A solid plan is usually the one that stays adjustable, so it can shift with the shifting markets, and also with the persons real life requirements.
FAQs
Q1. What is the 2027 COLA?
A. The 2027 COLA is a cost-of-living adjustment intended to help Social Security benefits keep pace with inflation.
Q2. Can retirees guarantee a 4% return?
A. No. A 4% return is a target, not a guaranteed outcome, and investment returns can fluctuate.
Q3. How can retirees prepare for the 2027 COLA?
A. Retirees can review their budget, maintain emergency savings, and balance income needs with investment risk.
Social Security COLA 2027: When Will the New Increase Be Announced?
Millions of Social Security recipients in the U.S. keep a close watch on the COLA, or Cost-of-Living Adjustment every year. The reason is pretty clear, changes to the COLA directly change monthly Social Security payments, and people notice it fast. There is also this rising anticipation among beneficiaries about what the COLA might look like for 2027, and honestly it’s been on a lot of minds. Still the biggest questions right now feel simple but loaded: when will the official announcement for the 2027 Social Security COLA actually happen, and what sort of adjustment can beneficiaries expect from it?
What is COLA 2027, and why is it important?
The whole point of the COLA is basically to tune Social Security benefits so they can keep up with inflation. When the cost of daily goods ,services, and these other essential expenses starts rising, then adjusting benefits does help—at least to a degree—so retirees and other beneficiaries can still afford the stuff they need. So if you are waiting for the yearly COLA announcement, it is not only some number. It is a key update tied to what their budget and expenses will look like in the next year.
When will the Social Security COLA 2027 be announced?
The Social Security COLA is usually made official in October. For 2027, the COLA might be announced during the same yearly rhythm, you know. Still, it would be a mistake to expect a particular day ahead of time. The relevant federal authorities will publish the final adjustment details once the official numbers are ready. So basically, beneficiaries should keep their attention on the actual announcement, and not on rumors, or even those little speculations that bounce around social media.
How is the COLA calculated?
The COLA get decided based on a particular inflation measure, and the numbers that are actually in hand during the third quarter of the year are used for that. So for that reason, those early-year estimates about the 2027 COLA don’t really match what will be the final figures , because once more inflation data starts showing up, the forecasted uplift might shift a bit.
Will every Social Security beneficiary receive the same increase?
While the percentage adjustment for the COLA generally applies to benefits, the actual dollar increase can be different depending on the person, kind of. You see, the monthly benefit amounts being currently received by beneficiaries are not the same for everyone. So, even if the COLA percentage is identical, the real uptick in monthly payments for two individuals might not match up exactly, or at all.
When will the impact of the 2027 COLA be seen on monthly payments?
The adjusted benefit amount kicks in during the year after the COLA gets announced, so the real effect of the 2027 COLA will show up in beneficiaries Social Security payments for 2027. That said, the exact timing of the payment can shift a bit, depending on the person’s particular situation and their payment schedule. Because of this, just knowing the COLA percentage by itself is not really enough, beneficiaries should also watch their own payment info, like the exact statement details.
What should beneficiaries keep in mind?
About the 2027 COLA projections, the main thing is that there can be a mismatch between what people estimate and the official number. Inflation is always shifting , so those early forecasts really should not be treated as the last word for the final announcement. In the meantime, beneficiaries should follow the official notices coming from Social Security and not act like any projected amount is guaranteed in their monthly budgets, until the final COLA gets announced.
Does a COLA increase mean expenses might rise too?
An increase in Social Security payments can give some relief, but it doesn’t automatically mean a beneficiary’s financial situation will just get better. If the price of groceries, housing , healthcare, and other essential services keeps climbing because of inflation, then that larger benefit might only be absorbed to pay for those higher, day-to-day costs. So it’s worth looking at the COLA in the wider sense of the household budget, not only as a number by itself.
What can be expected regarding the 2027 COLA right now?
Various projections about what the 2027 Social Security COLA might look like could show up, but honestly the real percentage won’t be locked in until the official announcement happens. The most cautious idea for beneficiaries is to see the estimated numbers as just a reference point for planning, not as something set in stone , and to only make the final choices once the official figure is out.
Conclusion
The 2027 Social Security COLA will be kinda a big financial update for millions of beneficiaries. The official COLA announcement typically takes place in October, and the final increase depends on inflation data, so yeah it’s still early. So it would be premature to treat any estimated percentage as definitive, at this stage anyway. Once the official announcement is made though, people will be able to see how much their monthly Social Security benefits might change, and then plan their 2027 expenses in a more measured way.
FAQs
Q1. When will the Social Security COLA 2027 be announced?
A. The 2027 COLA is generally expected to be announced in October 2026.
Q2. How is the Social Security COLA calculated?
A. The COLA is based on inflation data measured through a specific federal index.
Q3. When will the 2027 COLA increase affect payments?
A. The adjusted benefit amounts are expected to take effect with Social Security payments in 2027.
Latest Social Security COLA: What Beneficiaries Need to Know
For millions of Americans who are getting Social Security checks, the Cost-of-Living Adjustment, or COLA, is one of those big yearly shifts that nobody really ignores. The Social Security Administration just said there will be a 2.8% COLA for 2026. I mean, the point of this is to help keep the buying power of benefits steady, kinda by factoring in inflation and the overall climb in everyday expenses. That 2.8% step started impacting Social Security recipients in January 2026, but the change for SSI payments actually began on December 31, 2025.
How much did Social Security benefits increase in 2026?
A 2.8% COLA basically means eligible Social Security benefits, for most people, went up around 2.8%. Still the real dollar raise that a person actually feels can be a bit different, because it depends on what they’re already getting and a few deductions here and there. Per the Social Security Administration, the typical benefit for a retired worker moved from roughly $2,015 to $2,071 per month, so overall that works out to an average monthly climb of about $56.
Why is COLA provided?
The main purpose of the COLA is to nudge Social Security and SSI payments so they can reflect the effects of inflation, sorta like staying in step. It gets figured out by looking at how the Consumer Price Index for Urban Wage Earners and Clerical Workers, (CPI-W) changes over time. The 2.8% adjustment for 2026 was set after comparing the third-quarter CPI-W average numbers from 2024 and 2025. So basically the COLA is done once a year using a fixed equation or routine, not tailored from what each individual beneficiary might spend.
Not every beneficiary will receive the same dollar increase

It’s important to understand that a 2.8% COLA doesn’t really mean that everyone gets the exact same dollar figure. In practice, people with higher, current benefits will usually get a bigger dollar adjustment, while those with lower benefits might see a smaller change. Also the final amount that ends up being deposited into your bank account can shift a bit, because of things like Medicare premiums, or other deductions that apply. So the most reliable way to find your specific updated benefit level is to look over your own Social Security notice, the one made just for you.
Increase in SSI Benefits for 2026
The COLA isn’t just for Social Security retirement checks by itself, ya know. Supplemental Security Income (SSI) payments will also climb by 2.8% in 2026. As the SSA puts it, the federal SSI payment standard for 2026 is $994 per month for an eligible person , and $1,491 per month for an eligible couple. Still the payment you actually get might be different, depending on someone’s situation, other money coming in , or specific eligibility details.
What should beneficiaries keep in mind?
After the 2026 COLA, beneficiaries should probably check what their new benefit amounts look like, and then update their monthly budgets as needed, a little slower than you might think. Even with the COLA increase, it’s possible that costs for housing, food, utilities , healthcare, and other day to day expenses will climb too; so it might not be wise to sign on for extra spending just because the check went up. The Social Security Administration has also put personalized COLA notices in front of beneficiaries, and you can view the details online through a “my Social Security” account, if you’d rather not wait for mail .
What does the 2026 COLA mean in practical terms?
So, the 2.8% COLA for 2026 is basically a big annual tweak to benefits people already get, especially for Social Security and SSI. Even though this change is going to show up as a different dollar amount for each person, the main idea is to bring the benefit value in line with rising prices. Still, the most important move for beneficiaries is to look over the notice they personally received, make sure the real payment amount is correct, and then use that extra money in a sensible way inside their overall, monthly budget.
FAQs
Q1. What is the latest Social Security COLA?
A. The latest Social Security COLA is 2.8% for 2026.
Q2. When did the 2026 COLA take effect?
A. The increase began with Social Security payments in January 2026.
Q3. Will every beneficiary receive the same increase?
A. No. The dollar increase depends on each beneficiary’s current benefit amount.
Social Security COLA Payments Rising in 2026: Find Out How Much You’ll Get
Every year, millions of Social Security recipients kind of keep a close watch on the Cost-of-Living Adjustment (COLA) , because this bump directly hits their monthly benefits. For 2026, a COLA based increase in Social Security payments has been put in place, meant to help beneficiaries keep their purchasing power while inflation stays higher and daily necessities keep getting more expensive. Still, the actual amount a person receives depends on their personal benefit history, the age when they claimed , and what’s on their Social Security record. So, the increase is not the same across every beneficiary, it varies quite a bit.
Why is the COLA implemented?
The primary purpose of the COLA is to adjust Social Security benefits in line with the impact of inflation. When the prices of groceries, housing, healthcare, transportation, and other necessities rise, the amount that previously covered monthly expenses may prove insufficient in the future. The COLA provides an annual adjustment to benefits to help balance this gap to some extent. While this does not necessarily mean an individual’s overall financial situation will improve, the increased payment can offer some additional financial support amidst rising costs.
How much might you receive?
Your Social Security payment amount for 2026 cannot be determined solely by looking at the COLA percentage; your current benefit amount serves as the most critical baseline.

For instance, if a beneficiary currently receives a monthly benefit of $1,500, the new amount will increase based on the COLA percentage applied to that figure. Conversely, an individual receiving a higher or lower benefit would see a different final increase. Therefore, estimating your new payment amount based on someone else’s payment would be inaccurate.
Who might be affected?
The COLA adjustment is significant for various categories of Social Security beneficiaries, including retired workers, those with disabilities, and survivors. However, the exact benefit calculation varies according to each individual’s circumstances. Since some people may receive Supplemental Security Income (SSI) or other sources of income alongside Social Security, the change in total monthly income is not determined solely by the Social Security payment.
How should the increased amount be used?
The increased monthly payment might seem small, but its impact can be significant over the course of a year. Beneficiaries can use this extra money for groceries, utility bills, medical expenses, transportation, or other essential household costs. Some may even choose to set it aside for emergency savings. For those living on a fixed income, in particular, this additional monthly amount can help make their budget a bit more manageable.
Be Sure to Check Your New Social Security Benefit Amount
Most importantly, you should consult official Social Security information and your personal benefit statement to determine the exact payment amount. Estimated figures or amounts shared on social media do not apply to everyone; the final amount varies based on your individual benefit history and other factors. Therefore, the best way to understand the increased COLA payment for 2026 is to review your personal benefit information.
Conclusion
The 2026 Social Security COLA adjustment is significant for those who rely on Social Security benefits to cover their regular expenses. While the increased payment aims to mitigate the impact of inflation to some extent, the new amount received will differ for each beneficiary. Consequently, rather than focusing solely on news of the COLA increase, it is more useful to pay attention to your actual monthly benefit amount. Always prioritize official Social Security updates and your personal benefit records to ensure you have accurate information.
FAQs
Q1. What is the Social Security COLA for 2026?
A. The 2026 COLA increase raises Social Security benefits to help offset higher living costs.
Q2. How much will Social Security payments increase in 2026?
A. The increase depends on your current benefit amount and individual Social Security record.
Q3. When will the higher Social Security payments begin?
A. The adjusted payments are reflected in beneficiaries’ 2026 payment schedules.
VA COLA Increase 2027: Find Out Your New Monthly Benefit Rate
Veterans who receive VA disability compensation often pay real close attention to the annual Cost-of-Living Adjustment, or sometimes they just say COLA. This yearly tweak can lift monthly VA disability payments so benefits stay in line with what things cost day to day. Now as 2027 starts getting closer, a lot of veterans and their families are asking around about just how much their monthly amounts could go up and what the fresh benefit rates might look like. The exact 2027 VA COLA percentage has not been officially locked in, but grasping how the adjustment runs can give beneficiaries some breathing room to plan for possible changes.
What Is the VA COLA Increase?
The VA COLA is an annual adjustment designed to account for inflation and changes in the cost of living. VA disability compensation rates are generally adjusted in line with the Social Security COLA, meaning the final increase depends on the official COLA calculation. When the adjustment is applied, eligible veterans can receive a higher monthly compensation amount without needing to submit a new disability claim simply because of the COLA change. The purpose is to help maintain the purchasing power of benefits as everyday expenses increase.
How Could the 2027 Increase Affect Monthly Benefits?
The impact of the 2027 COLA will depend on a veteran’s individual disability rating and circumstances. Veterans with higher disability ratings generally get larger monthly payments, so the same percentage jump can turn into a different dollar amount for different beneficiaries.

On top of that, extra benefits for eligible dependants or other qualifying circumstances can also nudge the whole total amount that’s received, depending on each person’s case. For this reason, veterans should look at their specific benefit rate rather than assuming that everyone will receive the same dollar increase.
When Will the 2027 VA COLA Be Known?
The whole 2027 adjustment thing is kind of expected to get more clear after the official COLA announcement for 2027. Since VA compensation adjustments are linked to the yearly COLA cycle, beneficiaries should be careful with online articles, or social media posts, that talk about a possible percentage like it’s already official. Those numbers are only projections, and they can swing around as inflation data moves forward, so keep that in mind. The safest approach is to wait for official information before making financial decisions based on a specific increase.
Why the Increase Matters to Veterans
For many veterans, VA disability compensation somehow helps a lot with monthly household expenses, like it really adds up. Even a pretty small percentage increase can make a noticeable difference over the whole year, especially since prices for groceries, utilities, housing, transportation, and healthcare keep shifting. With a higher monthly benefit, families may get a bit more breathing room for household budgets, putting money aside for debt payments or other necessities that matter day to day.
How to Check Your New Benefit Rate
Once the 2027 rates are officially available, veterans really ought to take a look at their VA payment details and compare the newly posted amount with what they were getting each month before. It matters, not just in a general sense, but because the disability rating, dependent status, and a few other conditions can quietly shift the payment. Veterans should lean on official VA updates and the agency resources to verify their own benefit value, instead of depending only on broad web calculators or unverified guesses.
Stay Updated Before Planning Your Budget
The 2027 VA COLA increase could provide a welcome adjustment for veterans receiving disability compensation, but the final percentage and resulting payment amounts should not be treated as confirmed until officially announced. Keeping track of official updates and reviewing your individual benefit information will give you the clearest picture of what to expect. Until then, any projected increase should be viewed as an estimate rather than a guaranteed new monthly rate.
FAQs
Q1. What is the VA COLA increase for 2027?
A. The official 2027 VA COLA increase has not yet been announced.
Q2. When will the 2027 VA COLA be announced?
A. The 2027 COLA rate is expected to be announced in October 2026.
Q3. How will the VA COLA increase affect monthly benefits?
A. Eligible veterans may receive higher monthly benefit payments after the increase takes effect.
Social Security COLA Increase 2027: What Beneficiaries Need to Know
Every year millions of Social Security folks keep a close eye on the Cost-of-Living Adjustment (COLA), because that bump can hit their monthly benefits right in the middle. At the moment, there has not been a final official word about the 2027 Social Security COLA, but talk about a possible increase has already started in the background. The whole idea behind COLA is to soften the effect of rising everyday expenses from inflation, so beneficiaries can hold on to buying power, at least a bit, even when prices creep up.
What does the 2027 COLA mean?
COLA, or Cost of Living Adjustment, is a yearly tweak made to Social Security benefits so they keep up with inflation. When costs for food, housing, healthcare, and other necessary items go up, those Social Security payments get adjusted based on the official rules, not just guesswork. In that case the possible increase in 2027 matters a lot for beneficiaries, especially people who depend mostly on Social Security checks as their main income.
How much of an increase might occur in 2027?
The actual COLA percentage for 2027 has not yet been determined. Experts estimate potential increases based on various economic data and inflation trends, but these estimates should not be considered final figures. Beneficiaries will only know the exact increase in their monthly Social Security payments once the official COLA is announced. Therefore, it is advisable to wait for the official announcement rather than immediately altering one’s budget based on estimates.
When might the increased payment appear?
The COLA is usually announced around October, and then the new adjustment kind of kicks in for Social Security payments during the next year. So once the 2027 COLA takes effect, people may end up getting the higher amount based on their scheduled payment dates. However, the actual payment date may depend on the individual’s benefit category and the Social Security payment schedule.
What should beneficiaries keep in mind?
Looking solely at the COLA percentage is not enough. If an individual’s benefits increase, other deductions or circumstances could still affect the actual amount they receive. Because of things like Medicare premiums, taxes, or other adjustments, the real take-home amount might not go up by the full size of the COLA jump. So beneficiaries should watch their Social Security statements and check official info, really closely.
Why is the 2027 COLA kind of a big deal?
When prices are rising, even a modest monthly raise can end up meaning a lot over time. Lots of people depend on Social Security payments to handle housing, groceries, utilities, healthcare, and other day-to-day costs. In that sense the 2027 COLA isn’t just a number; it can shape beneficiaries’ household budgets and their financial planning for the next year.
Awaiting the final announcement is crucial
While speculation and discussions regarding the 2027 Social Security COLA may circulate, the final percentage will only be confirmed through an official announcement. The best approach for beneficiaries is to treat estimated figures merely as a reference for planning and to base their final decisions on official Social Security information. Since the new COLA increase will affect monthly benefits in the coming year, reviewing expenses and budgets in advance would be a prudent step.
FAQs
Q1. What is the Social Security COLA for 2027?
A. The official 2027 COLA has not yet been announced.
Q2. When will the 2027 Social Security COLA be announced?
A. The 2027 COLA is generally expected to be announced in October 2026.
Q3. When will the 2027 COLA increase take effect?
A. The increase is expected to appear in Social Security payments beginning in 2027.